
Curaleaf Shares Slide Sharply as Investors Question Takeover Terms
Authored by cannabiscanadabuzz.com, 16 Oct 2026
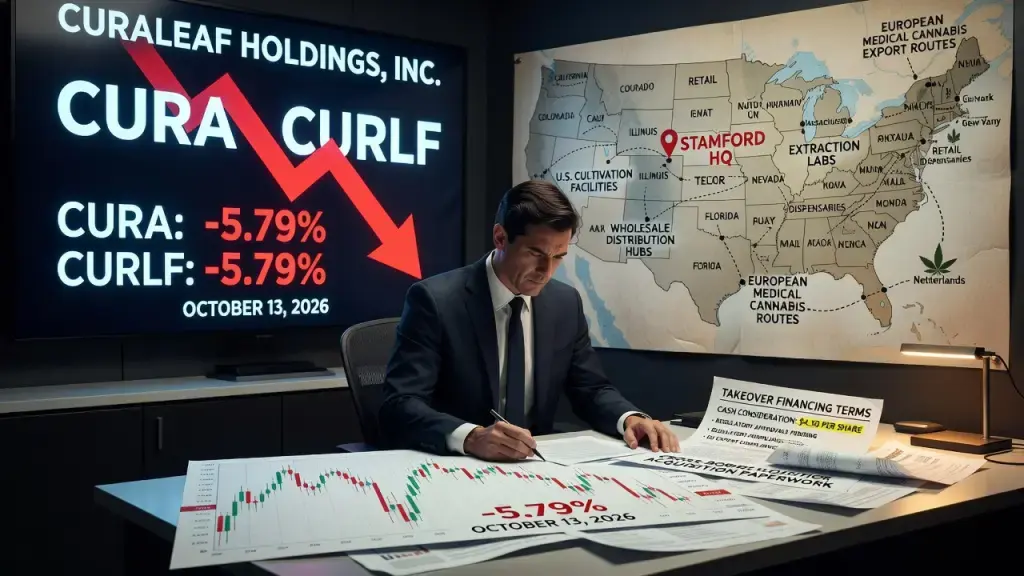
Curaleaf Holdings, Inc. (TSX:CURA; OTCQX:CURLF) shares fell 5.79% on the Toronto Stock Exchange on October 13, 2026, a single-session drop steep enough to signal more than routine profit-taking. The Stamford, Connecticut-based multi-state operator, which runs cultivation, extraction, wholesale distribution, and retail operations across the U.S. alongside a growing medical cannabis export business in Europe, is currently navigating a large cross-border acquisition. That combination - a sizable deal under negotiation plus a volatile trading tape - is exactly the kind of setup that makes institutional holders nervous.
Why the Sell-Off Reads as More Than Noise
A near-6% one-day decline doesn't happen in a vacuum. For multi-state operators, federal illegality still means no listing on senior U.S. exchanges, limited institutional custody options, and thinner trading books on venues like the TSX. That structural reality matters here: moderate liquidity can turn a modest wave of selling into an outsized price move, simply because there isn't enough standing buy-side depth to absorb it cleanly. Add in active cross-border takeover financing - cash consideration, shareholder vote dynamics, competition-authority review - and you get a stock where sentiment swings fast and hard. In practice, though, this is less about Curaleaf's day-to-day retail performance and more about how the market is pricing deal risk and post-merger integration uncertainty.
The Sector Pressures Sitting Underneath the Stock
Curaleaf doesn't trade in isolation. Multi-state operator peer groups have faced sustained valuation compression as institutional allocators rotate toward large-cap, diversified consumer and healthcare names with cleaner regulatory profiles. Several structural headwinds compound that rotation:
- Wholesale flower and concentrate price compression in maturing state markets, which squeezes gross margin and inventory valuations
- Internal Revenue Code Section 280E, which disallows standard deductions for plant-touching businesses and inflates effective tax rates well beyond what non-cannabis retailers pay
- Elevated benchmark borrowing costs, which raise the bar for refinancing senior secured debt facilities tied to retail build-outs and acquisitions
- Persistent federal rescheduling delays, which continue to block interstate commerce and mainstream banking access
None of this is new to operators who've been tracking the space. But it's worth saying plainly: these aren't temporary frictions. They're the operating floor every U.S. plant-touching company works above, and they shape how much credit the market extends to growth stories, cross-border or otherwise.
What Dispensary Operators and Suppliers Should Watch
For store-level operators, wholesale partners, and brand licensors tied into Curaleaf's retail and distribution network - Select, Grassroots, JAMS - the relevant signal isn't the ticker symbol itself. It's what equity-market stress implies about capital discipline upstream. When a multi-state operator faces a higher cost of capital, that pressure tends to travel downstream: slower retail dispensary approvals, more conservative capacity utilization decisions in transitioning state markets, and tighter terms on wholesale menus. Landlords negotiating retail leases, payment processors servicing cashless transaction systems, and software vendors supporting seed-to-sale tracking and compliance logs should treat balance sheet headlines as early indicators, not background noise.
The Integration Question Nobody Can Skip
Cross-border acquisitions sound tidy in a press release. Executing one - reconciling compliance frameworks across U.S. state regulators and European medical cannabis authorities, aligning cultivation and extraction standards, merging corporate cultures - is a different exercise entirely. Shareholder resistance, regulatory review timelines, and integration friction all extend the window before synergies show up in reported earnings. Until that happens, expect the market to keep demanding proof: durable operating margins, disciplined deleveraging, and export shipment velocity that actually materializes on schedule rather than on paper. That's the bar multi-state operators now have to clear before premium multiples come back.